Summary
Long-term care insurance for Assisted Living can help offset costs, though coverage varies significantly by policy and individual circumstances. Understanding your benefits before moving allows families to plan finances and confirm what the community's services will cost out-of-pocket.
- Many policies cover Assisted Living if the policyholder meets specific triggers, such as needing help with at least two Activities of Daily Living or having a qualifying cognitive impairment
- Benefits typically apply to apartment costs, meals, personal support with bathing or dressing, medication management, housekeeping, and services related to cognitive needs
- Contact your insurance company before the move to request a benefits summary, understand the claims process, and confirm which community services qualify for coverage
- Review waiting periods, daily or monthly payment caps, lifetime benefit limits, and reassessment requirements that may affect your coverage
- Plan for out-of-pocket expenses like personal purchases, salon services, and optional activities that insurance typically doesn't cover
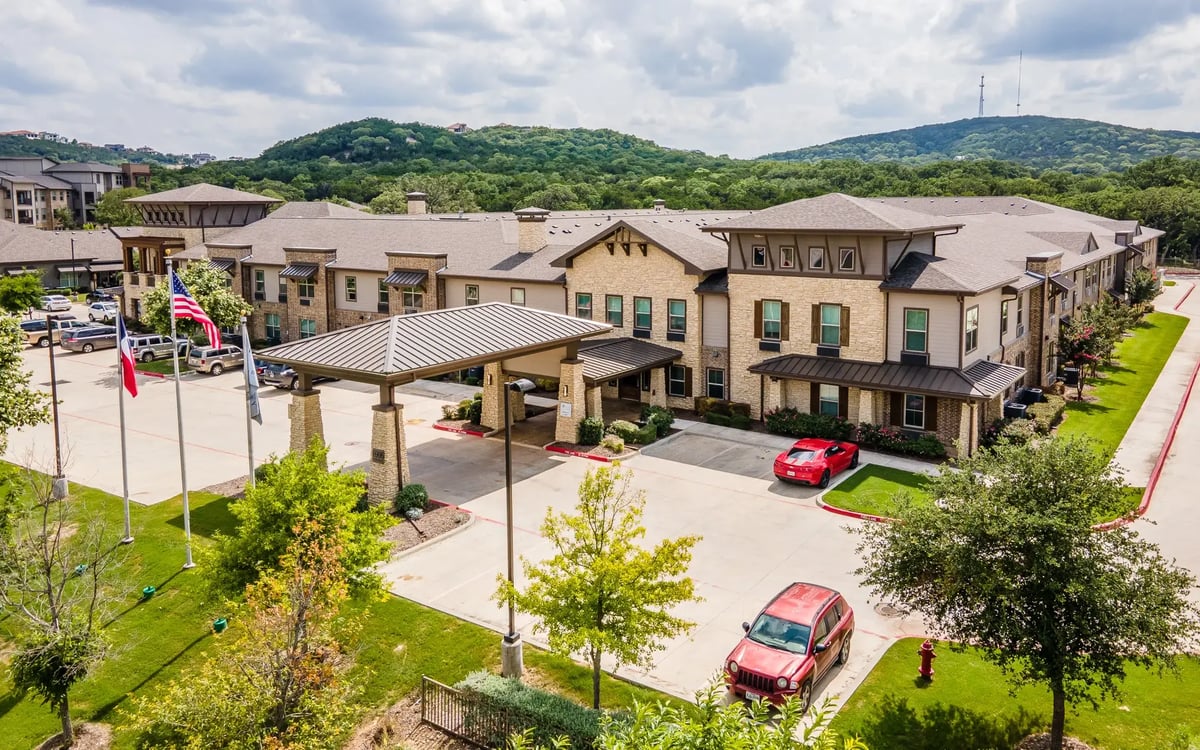
Long-term care insurance can be a valuable resource when a loved one needs help with everyday routines. Many policies provide benefits for assisted living, although eligibility requirements, payment amounts, and covered services vary. Families considering Discovery Village Dominion in San Antonio can begin by reviewing the policy alongside the community’s services and current pricing.
Understanding the policy before a move gives families time to confirm coverage, collect documentation, and plan for expenses insurance may not pay. Starting early can also prevent delays once support is needed.
Understanding Long-Term Care Insurance and Assisted Living
Long-term care insurance helps cover qualifying support that standard health insurance and Medicare generally do not pay for on an ongoing basis. Does LTC insurance cover assisted living? Many policies do, but benefits are usually triggered only after the policyholder meets specific medical or functional requirements.
A common benefit trigger is needing help with at least two Activities of Daily Living, such as bathing, dressing, eating, transferring, toileting, or continence. Some policies also provide benefits when a person has a qualifying cognitive impairment.
Review the policy’s definition of assisted living carefully. The insurer may require the community to meet licensing or service standards. Discovery Village Dominion Assisted Living is licensed in Texas and provides personalized help with daily routines in a resort-style senior living setting.
What Does LTC Insurance Pay For?
The answer depends on the individual contract. Some policies pay a fixed daily or monthly benefit, while others reimburse eligible expenses up to a stated limit.
Depending on the policy, assisted living insurance coverage may contribute toward:
The apartment, meals, and qualifying community charges
Personal support with bathing, dressing, grooming, or mobility
Medication management and scheduled wellness checks
Housekeeping, laundry, and other eligible daily services
Support associated with a documented cognitive impairment
Insurance may cover all or only part of these costs. Review the maximum daily or monthly benefit and compare it with the full community rate.
The Assisted Living program at Discovery Village Dominion includes chef-prepared meals, weekly housekeeping, scheduled transportation, community events, and personalized assistance. Ask the insurer which portions of the monthly fee qualify under the policy.
How to Start Using Insurance for Senior Living
Contact the insurance company before the planned move. Request a current benefits summary and ask for written instructions explaining how to open a claim.
The claims process commonly involves:
Completing policyholder and authorized-representative forms
Providing medical records or a physician’s statement
Completing an assessment of daily support or cognitive needs
Submitting the community’s license, service plan, and billing information
Receiving approval before regular benefits begin
Discovery Village Dominion’s team may be able to provide community records and billing documents requested by the insurer. However, the insurance company makes the final coverage decision.
Keep copies of every form, assessment, invoice, and letter. Record the date and details of each conversation with the insurer. Organized records can make follow-up easier if information is missing or a decision requires review.
Review Waiting Periods and Benefit Limits
A long-term care policy for assisted living may include an elimination period. During this waiting period, the policyholder remains responsible for eligible expenses before insurance payments begin. Depending on the contract, the period may be based on calendar days or days when qualifying services are received.
Other important limitations may include:
Daily or monthly payment caps
A maximum lifetime benefit
Requirements for recurring reassessments
Exclusions for certain services or supplies
Rules governing how inflation protection is applied
Confirm whether the policy reimburses the resident after bills are paid or sends benefits directly to the community. Also ask how often invoices and support records must be submitted.
Families can review floor plans and pricing to compare available Assisted Living apartment homes and build a realistic monthly budget.
Plan for Costs the Policy May Not Cover
Even a strong policy may leave a portion of the monthly bill unpaid. Personal purchases, salon services, optional outings, private transportation, and some medical supplies may fall outside the policy’s definition of eligible expenses.
Discovery Village Dominion offers signature senior living programs, including Sensations Dining, Expressions Concierge, Impressions Housekeeping and Maintenance, and Connections Transportation. Families should ask which services are included in the monthly rate, and which may involve an additional charge.
A financial advisor or elder law attorney familiar with long-term support planning can help compare insurance benefits with savings, retirement income, veterans' benefits, and other resources.
Frequently Asked Questions
Does Medicare Cover Assisted Living?
Medicare generally does not pay for ongoing room, meals, and personal support in assisted living. It may cover certain qualifying medical services received separately.
How Long Does an Insurance Claim Take?
Timing varies by insurer and depends on whether all assessments, records, and community documents have been submitted.
Can a Policy Pay the Community Directly?
Some policies allow direct assignment of benefits, while others reimburse the policyholder. Confirm the payment method with the insurer.
Long-term care insurance can make assisted living more manageable, but families should confirm eligibility, benefit limits, and uncovered expenses before making financial decisions.
To discuss apartment availability, included services, and documentation your insurer may request, schedule a tour of Discovery Village Dominion.